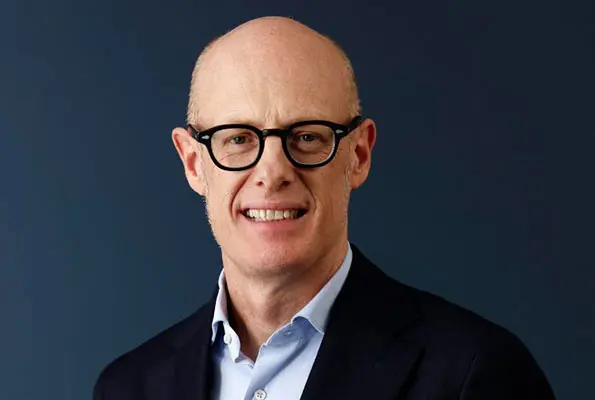
Amid the ongoing crisis in the German automobile industry that has resulted in brute company restructuring and job redundancies, Porsche CEO Michael Leiters has told the company staff there were no plans to cut an additional 4,000 jobs at the Volkswagen sports car subsidiary.
The CEO was responding to a Handelsblatt report that said Volkswagen’s supervisory board viewed another 4,100 jobs at the brand as unnecessary, on top of the 9,000 layoffs already agreed upon.
“There are no plans to cut an additional 4,000 jobs at Porsche. We do not anticipate any changes to it,” Leiters said, adding that the existing restructuring plan had already been approved by Porsche’s own supervisory board.
The Handelsblatt report, citing “files” that document a recent agreement by Volkswagen’s supervisory board, claimed that the parent brand proposed a reduction of “about 4,100 employees” at the sports car maker to address an overhead shortfall of approximately 700 million euros (USD 803.8 million).
In July this year, Porsche management and labour representatives agreed to an additional 5,000 layoffs on top of the 4,000 determined earlier, bringing the scope of currently agreed job cuts at the Stuttgart-based 911 maker to around one in five by 2035.
Volkswagen, last Friday, revised down its full-year margin target, now hoping for 1% at best rather than a previous range of 4.0-5.5%.
Along with the parent group’s CEO Oliver Blume, Leiters is facing the heat of delivering a comeback strategy following a collapse in China sales and a costly reversal of the carmaker’s EV strategy.
Porsche, earlier this month, completed the sale of its stakes in Bugatti Rimac and Rimac Group, marking its exit from the Croatian electric hypercar maker and related businesses.
The transaction generated proceeds of around 1 billion euro (USD 1.2 billion) for the German sports car manufacturer.
While Porsche sees the deal helping lift its 2026 automotive net cash flow margin forecast to 5.5%-7.5%, from the previous ratio of 3%-5%, it also plans to allocate 250 million euros of the proceeds to further fund pension obligations.
Image Credit: Porsche