For most of the past three years, the trade on artificial intelligence has been simple enough to fit on a napkin. Buy Nvidia. Everything else was a footnote.
That is no longer true. The chips are only part of what an AI data centre needs. Each one also needs an enormous and reliable supply of electricity, the transformers and switchgear to move it around, and increasingly exotic cooling to stop the racks from melting. A second tier of suppliers has grown up to meet that demand, and their order books have never looked better.
What has changed in 2026 is that the market has stopped rewarding all of them. Some have surged. Others have fallen hard, even while their orders climbed. The gap between the two groups is now the most interesting thing about the sector.
The demand itself is not in doubt
Start with the electricity, because that is where the physical limits bite first.
The International Energy Agency expects global data centre electricity consumption to more than double from 415 terawatt hours in 2024 to roughly 945 terawatt hours by 2030, which is about what Japan uses in a year today, and to keep climbing towards 1,200 terawatt hours by 2035. The United States accounted for 45% of global data centre electricity in 2024 and China for 25%. Demand from AI optimised facilities specifically is set to more than quadruple by the end of the decade.
The money involved is difficult to overstate. McKinsey estimates that data centres will require $6.7 trillion of investment worldwide by 2030, of which $5.2 trillion goes to AI capable capacity. For 2026 alone, BloombergNEF puts the combined capital spending of the 14 largest listed operators at close to $750 billion , against just under $450 billion in 2025. Delta Electronics told investors that the four largest cloud providers alone would lift spending from about $410 billion in 2025 to an estimated $670 billion in 2026.
Roughly three quarters of that goes to chips, servers, and networking. The remainder still leaves well over $100 billion a year flowing to power and cooling equipment, and that is the pool these companies are fishing in.
The bottleneck is physical, and it favours the incumbents
Money is not the constraint. Steel, copper and factory slots are.
GE Vernova’s gas power backlog and slot reservations reached 116 gigawatts by the middle of 2026, up from 83 gigawatts at the end of 2025. A heavy duty turbine ordered today will not be delivered until 2031. Combined cycle plant lead times have stretched from about three-and-a-half years in 2023 to roughly five, and as long as seven for certain frames. Siemens Energy closed its fiscal third quarter with a 69 gigawatt gas turbine backlog, and lead times of three years or more.
Transformers tell the same story. The IEA reports that lead times for large power transformers have almost doubled on average since 2021 and now run well beyond 24 months. Wood Mackenzie’s survey work put US power transformers at 128 weeks, and generator step up units at 144 weeks. Grid connection queues in some developed markets stretch past eight years.
For a supplier, a shortage of this kind is a licence to raise prices and refuse unattractive work. That is exactly what the better operators have been doing.
Cooling is the second bottleneck, and it is changing faster
A conventional enterprise server rack draws somewhere between 5 and 15 kilowatts. Nvidia’s GB200 NVL72 rack is specified at around 132 kilowatts, roughly ten times as much. The Vera Rubin platform now entering production pushes the figure to somewhere between 190 and 230 kilowatts, and the Rubin Ultra rack due in 2027 is designed for about 600 kilowatts. Bank of America expects power draw per AI rack to pass 1.5 megawatts by the end of 2030, close to a hundredfold increase on a conventional rack.
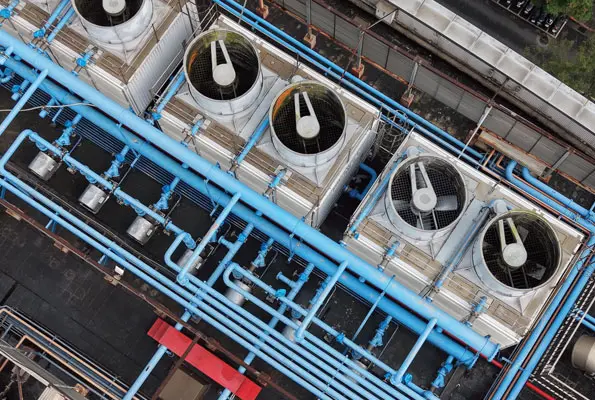
Air simply cannot move that much heat. Liquid cooling, whether direct to chip or immersion, becomes compulsory rather than optional. Bank of America forecasts that liquid cooling will account for 70% of new AI data centre installations by 2030, up from about 30% today. The same physics is forcing a shift to 800 volt direct current power architecture, which Nvidia announced in 2025 to make megawatt class racks workable at all.
Dell’Oro Group expects the data centre physical infrastructure market to grow at 22% a year to $120 billion by 2030, with thermal management the fastest growing slice. One detail in that forecast deserves attention. Dell’Oro expects annual net capacity additions to peak in year-on=year growth terms in 2026, and moderate afterwards. The market is still expanding quickly. It has stopped accelerating.
Six companies, three very different outcomes
The clearest winners have been the Taiwanese firms sitting inside Nvidia’s ecosystem.
Delta Electronics reported first quarter revenue of 159.4 billion Taiwan dollars, up 36%, with a record 37% gross margin, and net profit doubling. Second quarter revenue grew 48%. Delta showcased 800 volt direct current power racks, a 2.4 megawatt coolant distribution unit, and solid state transformers at Nvidia’s developer conference. Its shares are up more than 90% this year. Chairman Cheng Ping struck a confident note at the company’s second quarter earnings call on July 30, telling analysts that ‘the second half will definitely be better than the first half’, while conceding that the record first quarter gross margin would be difficult to match.
Asia Vital Components has done better still on growth. First quarter revenue rose 110% year-on-year to 49 billion Taiwan dollars, with gross margin improving to 32.57% in the following quarter. It supplies cold plates to a major US cloud provider for both custom silicon and GPU platforms, and has qualified into GB300, VR200, Google’s TPU, and Groq. Management points to order visibility running to 2029.
Auras Technology grew 2025 revenue 47.5%, and first quarter 2026 revenue 57.7%, with net profit up 139%. Liquid cooling should account for roughly 55% of its revenue this year. The shares are up around 70% over twelve months.
Then there is the odd case in the middle. HD Hyundai Electric of South Korea has arguably the strongest order position of any of them. Its backlog rose 23% to $8.5 billion at the end of June 2026, more than three years of work, and second quarter orders jumped 44.6%. It is in talks with three global technology firms over data centre power packages, and it is building a $200 million plant in Alabama. A deliberate policy of selective ordering, favouring high margin North American and Middle Eastern contracts, delivered a record 27.6% operating margin in the fourth quarter of 2025. And yet, the shares are broadly flat in 2026, well below their May peak, after more than doubling in 2025.
The pull is being felt across the whole Korean complex, where HD Hyundai Electric, Hyosung Heavy Industries, and LS Electric between them hold an order backlog above 36 trillion won. Writing on LS Electric in May, Lee Min-jae, an analyst at NH Investment and Securities, noted that ‘the North American data center customer base is thickening’, with the product range broadening from alternating current equipment into direct current systems.
The two Chinese names are where the pain has landed.
Hainan Jinpan Smart Technology grew first half revenue 12.73% to 3.556 billion yuan and net profit 14.23%. New data centre orders rose 336% to 3.87 billion yuan. Overseas revenue jumped 68% and now makes up 41.7% of the total, helped by a new production base in Virginia. The stock has still fallen nearly 30% this year after a 118% gain in 2025, hurt by copper costs and a 297% rise in financial expenses from convertible bond interest and currency losses.
Shenzhen Envicool has fared worse. First half revenue rose 17.24% but net profit fell 14.32%. After first quarter results showed revenue up 26% while profit dropped 82%, the stock hit its downside limit on two consecutive sessions and shed more than 16 billion yuan of market value in a single day. Liquid cooling, the business the market was paying for, accounts for only about 7 to 8% of revenue. Citigroup moved to a sell rating. The shares are down about 20% this year, after rising 244% in 2025 on a price to earnings multiple above 220 times.
Why the split, and what the analysts are saying
Bank of America’s Matty Zhao, the bank’s Asia Pacific head of research for basic materials, oil and gas, put the new mood bluntly to Reuters on September 2. Investors, she warned, should be alive to the risks, because not every supplier riding this theme can come out ahead. “You have to be cherry-picked for the leaders who actually get the customers,” she said.
Several banks are saying versions of the same thing. Morgan Stanley urges investors to separate demand risk from execution risk, and to favour suppliers with contracted backlogs, pricing power, and a diversified customer base over those whose forecasts assume every planned campus opens on time. JPMorgan describes a ‘selective bull market’ in which pricing power and balance sheet strength decide outcomes. UBS expects solid state transformers to reach 40% penetration by 2030, with Chinese manufacturers taking a major share. Jefferies has stuck with single name conviction, holding a buy on GE Vernova.
Several forces explain the derating. Valuations in parts of the group had run far ahead of earnings. Margins are compressing as competition arrives and components commoditise. Chinese domestic price wars have reclassified firms like Envicool from high margin technology plays to high growth manufacturers, which attract a very different multiple. Customer concentration is real, since most of these firms depend on Nvidia and a handful of hyperscalers. Everyone is expanding capacity at once. And investors are quietly asking whether the current pace of capital spending can hold.
The pattern is visible in the United States too, and it is instructive. Through late August, the companies that build and electrify – Powell Industries, Vertiv, Quanta, and GE Vernova – delivered strong gains. Merchant generators, such as Vistra, Talen, and Constellation, whose earnings depend on power prices and contracts not yet signed, fell on average. Eaton posted record Electrical Americas revenue. GE Vernova’s electrification orders from data centres in the first quarter exceeded the whole of 2025. Powell won a single data centre order worth more than $400 million. Signed backlogs beat promises.
The 1999 problem
The uncomfortable historical parallel is the telecoms equipment boom of 1999 to 2001. Lucent, Nortel and Cisco extended vendor financing to carriers, booked the resulting shipments as revenue, and wrote much of it off when those customers failed. Global telecom stocks lost more than $2 trillion of value between 2000 and 2002. Nortel fell more than 90% in a year. The fibre they laid became the backbone of the modern internet. The shareholders who paid for it were wiped out.
That echo is being voiced at the top of the market. Goldman Sachs analyst Eric Sheridan has said the circular financing arrangements in AI make him nervous, and that the period rhymes with the dot com era.
There are early signs worth watching. TD Cowen reported that Microsoft had cancelled US data centre leases totalling a couple of hundred megawatts, allowed more than a gigawatt of larger agreements to lapse, and slowed the conversion of qualification statements into leases. Microsoft disputed the reading and reaffirmed its spending plans. Power constraints themselves act as a ceiling on how fast capacity can actually be built. Chinese suppliers face the additional risk of tariffs and export frictions, even as they open American plants to sidestep them.
What to watch
The demand story stands up to scrutiny. The trade built on top of it has become much more demanding.
For investors, the useful test is no longer whether a company sells into AI data centres. Almost all of them now do. It is whether the company can name the customer, show the contract, and convert the backlog into cash at a decent margin. On that measure Delta, Asia Vital Components, and HD Hyundai Electric look better placed than their share prices in one case suggest, while the Chinese names need to prove earnings quality before the multiple returns.
The signposts for the next twelve months are straightforward. Watch hyperscaler capital spending guidance for 2027, since a plateau would hit the whole group. Watch gross margins at Delta and Asia Vital Components for evidence of commoditisation. Watch how quickly orders turn into revenue. And watch for any further lease cancellations or deferrals from the big four cloud providers.
Nvidia’s suppliers are no longer a single trade. They are a stock picker’s problem now.