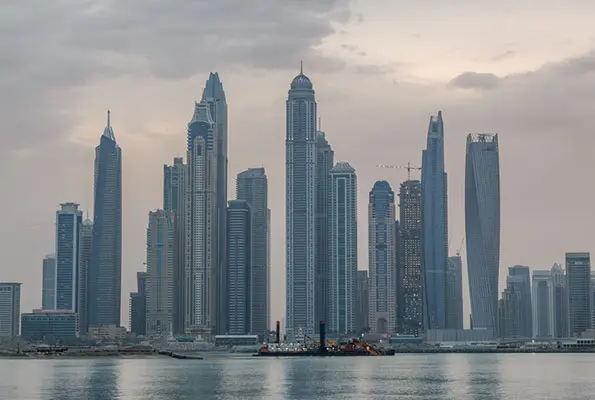
While Dubai’s property market has so far been able to avoid the widespread distressed selling anticipated by some buyers, Dubizzle Group sees the impact of rising housing supply on asking prices becoming more visible in the coming months.
Speaking at a media briefing in Dubai on Wednesday, Matt Gregory, Senior Director of Strategy at Dubizzle Group, said the sharp price correction expected by some market participants had not materialised in the advertised prices.
By the end of 2026, experts estimate that Dubai will welcome approximately 56,600 new residential units.
However, Gregory said the additional supply had not yet significantly affected asking prices in the communities tracked by Bayut, UAE’s largest property portal operated by Dubizzle Group.
Bayut’s third-quarter 2026 report showed the residential market stabilising, with limited changes in asking prices across the most popular communities.
Its fourth-quarter report, expected in January, should provide a clearer picture of how new housing supply is affecting the market, feels Gregory.
Average asking prices per square foot for affordable and mid-tier properties generally moved by less than 3% during the third quarter.
Most luxury and ultra-luxury segments recorded changes of less than 2%.
Four-bedroom villas in Al Barari were a notable exception, with average asking prices rising 8.2% quarter-on-quarter to Dh29.6 million. On Palm Jumeirah, four-bedroom villas averaged Dh44.1 million,” Gregory said.
Bayut recorded around 15 million platform visits during the quarter, an increase of 25% from the second quarter, while property listings rose 6%.
The growth came despite the summer months, when market activity typically slows as residents travel overseas.
Gregory said the figures reflected continued interest across affordable, mid-market and luxury residential communities.
Haider Ali Khan, CEO of Bayut and board member of the Dubai Chamber of Digital Economy, told the Khaleej Times the range of communities attracting interest highlighted the diversity of Dubai’s housing market.
“Across many of the popular areas in our report, asking prices have remained broadly steady, giving people more room to compare their options and plan their next move,” he said.
Palm Jumeirah remained among the most searched locations for ultra-luxury apartments.
Average asking prices rose 3.4% quarter-on-quarter to Dh3,490 per square foot, while Bluewaters Island and Al Barari also attracted interest in the segment.
Dubai Marina, Downtown Dubai and Dubai Hills Estate remained popular among luxury property seekers.
In the mid-tier apartment market, Jumeirah Village Circle (JVC) and Business Bay continued to attract buyers, with average asking prices of Dh1,419 and Dh2,158 per square foot, respectively.
Dubai Silicon Oasis led searches among more affordable apartment communities, followed by Dubai Sports City and Dubai South.
Studios in Dubai Silicon Oasis averaged Dh556,000, while one-bedroom apartments averaged Dh856,000.
For luxury and ultra-luxury villas, Dubai Hills Estate, Arabian Ranches, Al Barari and Palm Jumeirah remained popular choices.
“DAMAC Lagoons led searches in the mid-tier villa segment, with average asking prices of Dh1,499 per square foot. Arabian Ranches 3 and Al Furjan also attracted interest,” Dubizzle Group noted.
Among more affordable villa communities, DAMAC Hills 2, Rukan and Dubai South remained popular.
DAMAC Hills 2 recorded an average asking price of Dh1,054 per square foot.
Bayut’s analysis also identified communities with comparatively high estimated rental yields, highlighting differences in potential returns across property segments.
Dubai Investments Park recorded an estimated gross rental yield of 9.5% for affordable apartments, followed by Discovery Gardens at 8.5% and Remraam at 8.4%.
Living Legends recorded a 7.5% estimated yield in the mid-tier apartment category, while Al Sufouh offered 7.1% for luxury apartments.
For villas, Deira recorded an estimated 10% yield in the affordable segment, while The Sustainable City offered 6.1% for mid-tier properties.
The figures are estimated gross rental yields calculated using advertised prices and do not represent guaranteed investment returns.